Refurbishment appraisal
Price, value and the cost of time
The scope, cost and timing of a property project belong in the same appraisal.
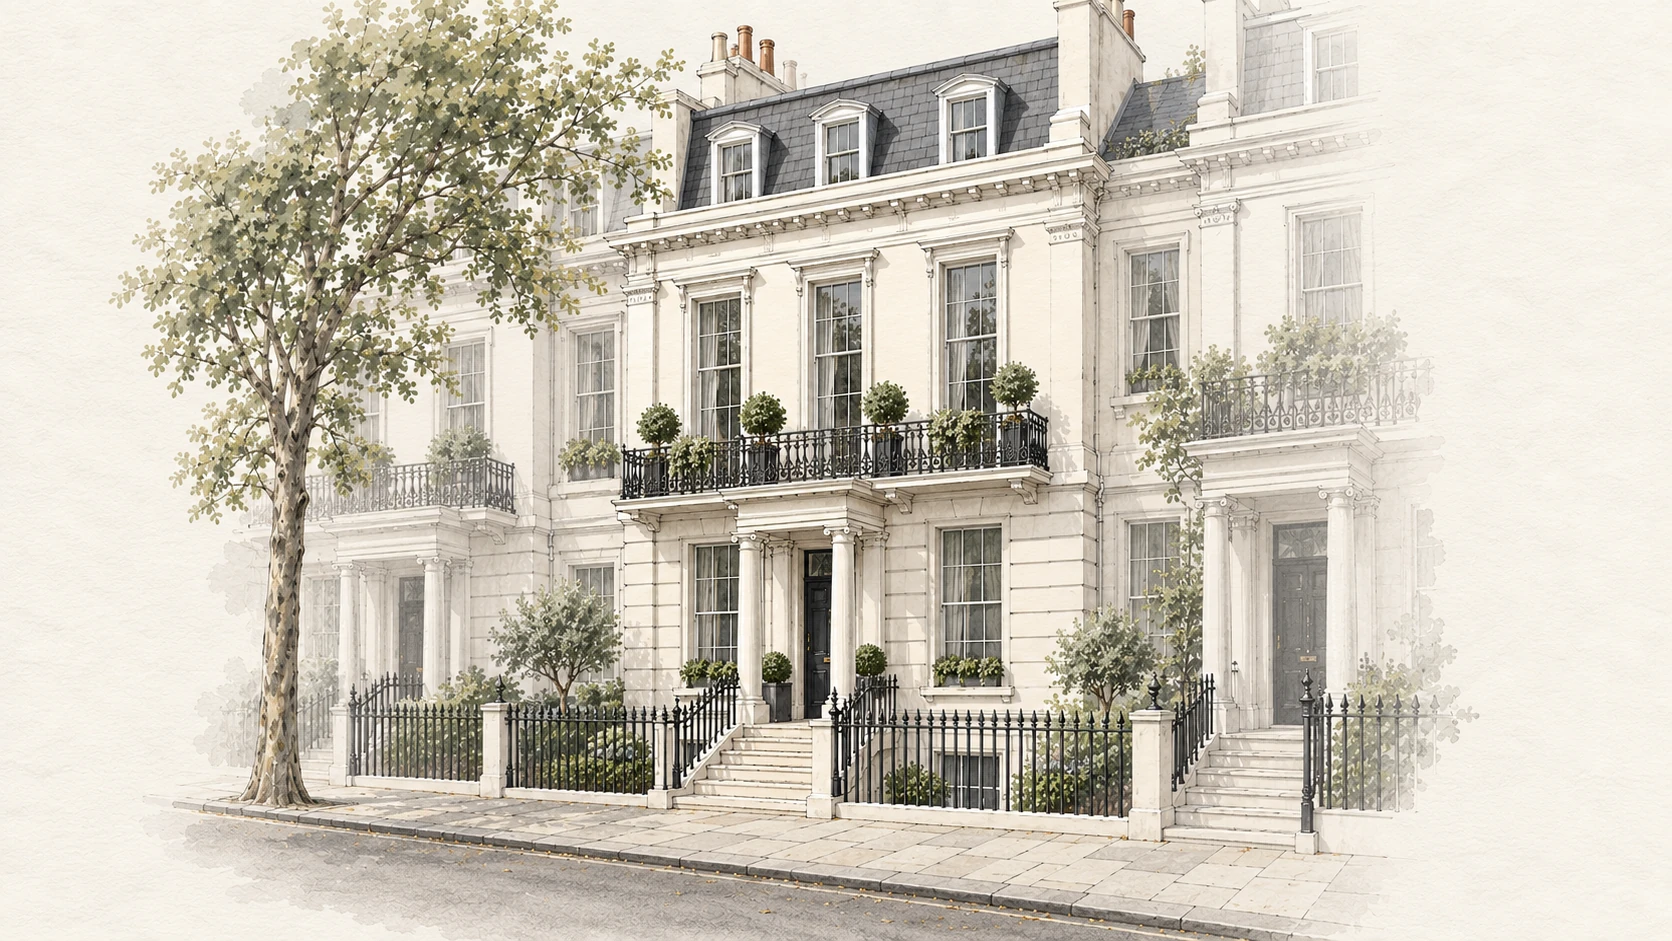
Architectural illustration
Begin with the existing property
An apparently inexpensive house can require extensive work before it is ready for resale. A higher purchase price may come with a different scope of refurbishment and a different programme. The comparison needs to explain what is being bought, what work is envisaged and what evidence supports the anticipated resale value.
Homes England's general appraisal guidance describes a residual approach: deducting costs from anticipated proceeds to examine what remains. It identifies refurbishment opportunities as one use of the method. It provides a framework for comparing assumptions about an existing property, rather than a conclusion about a particular project.
Connect the property to the scope of work
A property appraisal needs to account for the existing asset, proposed work, professional input, holding costs, finance and anticipated value. The construction quotation is one part of that account. Each allowance needs a stated scope and a clear relationship to the proposed programme.
The design questions come first. Which existing elements can be retained? What is known about the building's condition? Does an extension contribute enough to the proposed home to justify examining its additional work and time? These questions turn an attractive idea into a scope that can be discussed and costed.
Resale evidence needs similar care. A nearby sale is a starting point for comparison, but its relevance depends on the property itself. Size, configuration, condition, outdoor space and the date of sale deserve examination. The appraisal should make those differences visible rather than conceal them within a single assumed value.
Follow the money through time
Time affects when costs are incurred and when sale proceeds arrive. Homes England's guidance links interest charges to outstanding debt during the project. For a refurbishment, this means the sequence of acquisition, works and resale matters alongside the total expenditure. The effect of a delay depends on what has already been spent and the financing terms.
The rate assumption also needs a defined basis. The Bank of England explains that borrowing rates reflect market expectations, credit risk and other conditions. Bank Rate alone is not the interest rate offered for a particular project.
Scenarios can make this easier to discuss: a longer refurbishment, additional repair work or a later sale. Each scenario asks how a changed assumption affects the account. It describes a possible outcome, without pretending to know how likely that outcome is.
Sources: Financial viability for housing-led projects · About a rate of (general) interest: How monetary policy transmits
Keep the appraisal connected to the design
A revised layout or selective extension can alter the work, programme and intended resale proposition. The appraisal needs to move with those decisions.
That is the connection this journal examines: how an existing building, a proposed refurbishment and its financial assumptions fit together. Clear analysis shows the evidence and uncertainty behind the result. It does not convert an anticipated resale value into a guaranteed selling price or an appraisal margin into a promised return.
Sources and further reading
Read the evidence.
- Financial viability for housing-led projects
- About a rate of (general) interest: How monetary policy transmits
Sources checked 15 October 2026. This article is general commentary; the facts and constraints of a particular property require their own assessment.